
Key Factors
- Liquidia insiders have offered shares amid a patent settlement and analyst price-target cuts, although institutional shopping for and rising YUTREPIA gross sales supply some offsetting help.
- Brinker Worldwide insiders offered closely throughout a profitable Chili’s turnaround, however sturdy gross sales progress, margin positive aspects, and analyst optimism recommend the gross sales are much less regarding.
- Procter & Gamble’s insider gross sales seem tied to routine prearranged buying and selling plans, with analysts bullish on the inventory and the corporate sustaining sturdy money stream and dividend progress.
Insider buying and selling sends many alerts, however not all of them are what they appear.
Insider promoting generally is a inexperienced gentle for buyers or a warning to remain away; IT relies upon available on the market. Sector tendencies, the enterprise cycle, and an organization’s revenue outlook all affect how buyers ought to interpret these transactions. All else being equal, worthwhile corporations are extra invaluable than people who aren’t, separating true investments from hypothesis and danger.
Liquidia Insiders Liquidate After Dangerous Information
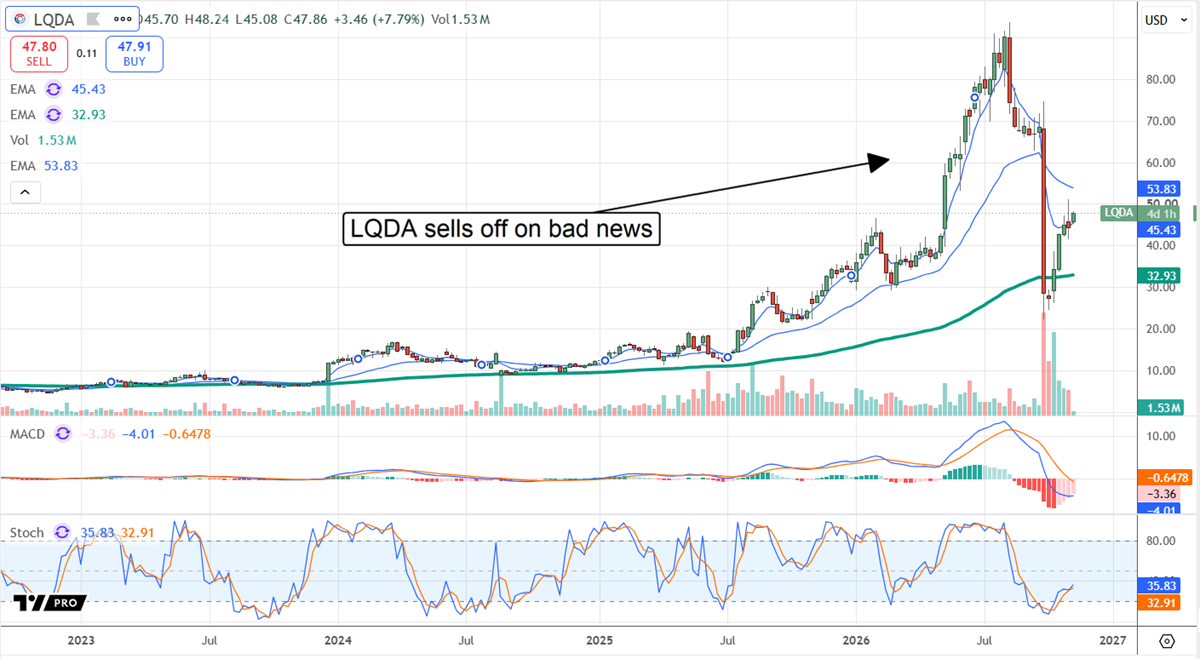
Liquidia (NASDAQ: LQDA) is a commercial-phase biopharma firm that reported unhealthy information this yr. Its major remedy, YUTREPIA, confronted a setback after a September patent ruling, however an October settlement with United Therapeutics resolved the litigation. Liquidia can proceed promoting YUTREPIA for pulmonary arterial hypertension, though IT should cease selling the drug for a separate indication and make substantial settlement funds. The settlement creates monetary challenges, however the firm’s rising gross sales present some reduction. In Q3, YUTREPIA sales climbed 31% sequentially to $222.7 million, at the same time as Liquidia recorded a $389.7 million cost associated to the settlement.
To make issues worse, insiders are promoting into the correction, serving to depress shares.
Insiders own 25% of LQDA shares and are a big drive, with a minimum of 9 executives with Chief of their title promoting for the reason that patent court docket ruling. Prearranged buying and selling plans account for a few of these gross sales, permitting executives to capitalize on excessive share costs and handle share-based compensation. Nonetheless, not all transactions fall underneath these plans. Many of those trades are open-market gross sales, suggesting a top-heavy managerial group could also be trimming extra danger.
Wall Avenue’s outlook for Liquidia has weakened, including to the inventory’s challenges.
Many analysts have slashed their price targets in current months, reflecting rising considerations about Liquidia’s outlook. Shares traded effectively under the $72.85 consensus goal in early November, though that hole additionally suggests potential upside if the corporate’s working efficiency continues to enhance.
Establishments personal about 65% of Liquidia shares, however institutional shopping for has exceeded promoting over the previous 12 months. Regardless of the current insider promoting, institutional help and bettering gross sales might assist offset among the inventory’s downward strain.
Chili’s Insiders Reap Rewards of Profitable Turnaround
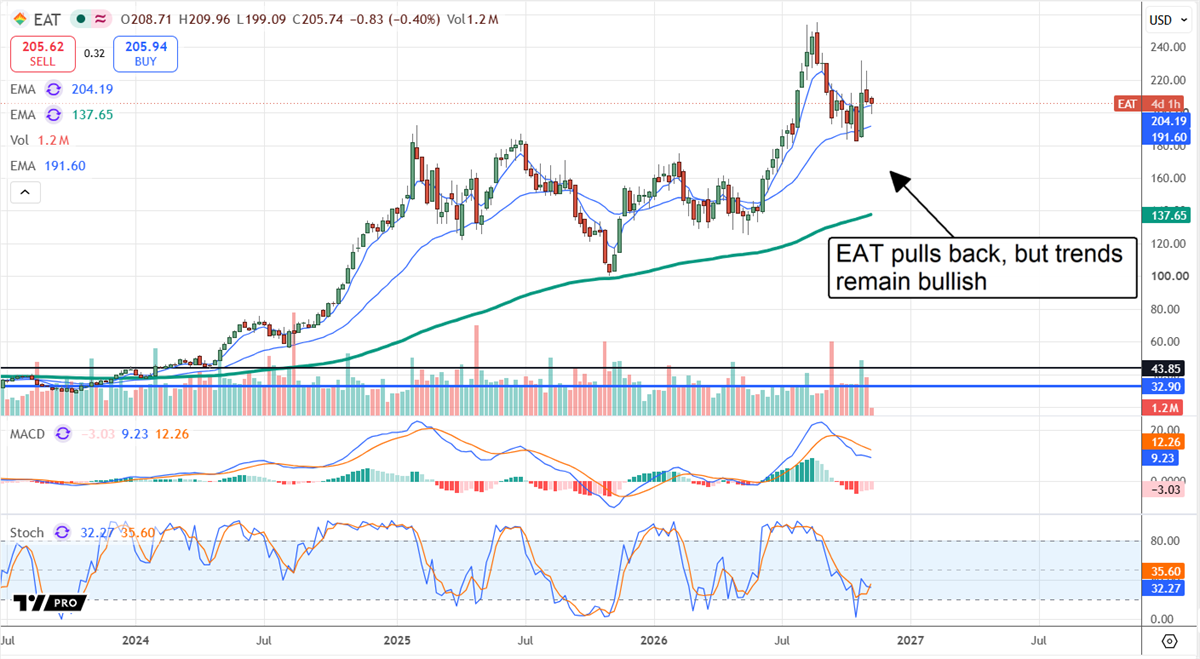
Chili’s dad or mum firm Brinker Worldwide (NASDAQ: EAT) noticed heavy insider promoting in Q3 and early This autumn, however the firm’s sturdy working efficiency suggests these gross sales could also be much less regarding than they initially seem.
The gross sales got here after two years of improving results, sturdy comparable gross sales, and margin positive aspects tied to a technique shift. Chili’s has embraced a “better-than-fast-food” strategy, providing worth meals and drinks that resonate with customers. The technique has helped drive sustained gross sales progress, widening margins, and accelerating earnings, with Chili’s gross sales up greater than 50% within the three-year stack.
Analysts like what they are seeing from EAT. Protection has elevated, sentiment has strengthened, and value targets have climbed, supporting the inventory’s Reasonable Purchase consensus ranking. The common value goal is up greater than 50% over the previous 12 months, and implies greater than 20% from October’s lows. Reaching that focus on would put shares at a recent all-time excessive.
The fiscal Q2 outcomes due in early 2027 might present one other catalyst for analysts to boost their targets if the corporate’s momentum continues.
Institutions own approximately 99% of EAT shares and have been internet consumers this yr, signaling confidence within the firm’s turnaround. The chance is that they distributed shares in early This autumn and will proceed to take action, limiting upside till the FQ2 launch. Enhancing efficiency at non-core manufacturers, increasing margins, sturdy money stream, and sustained comparable gross sales progress might encourage establishments to extend their holdings.
Procter & Gamble Insider Gross sales Elevate Few Pink Flags
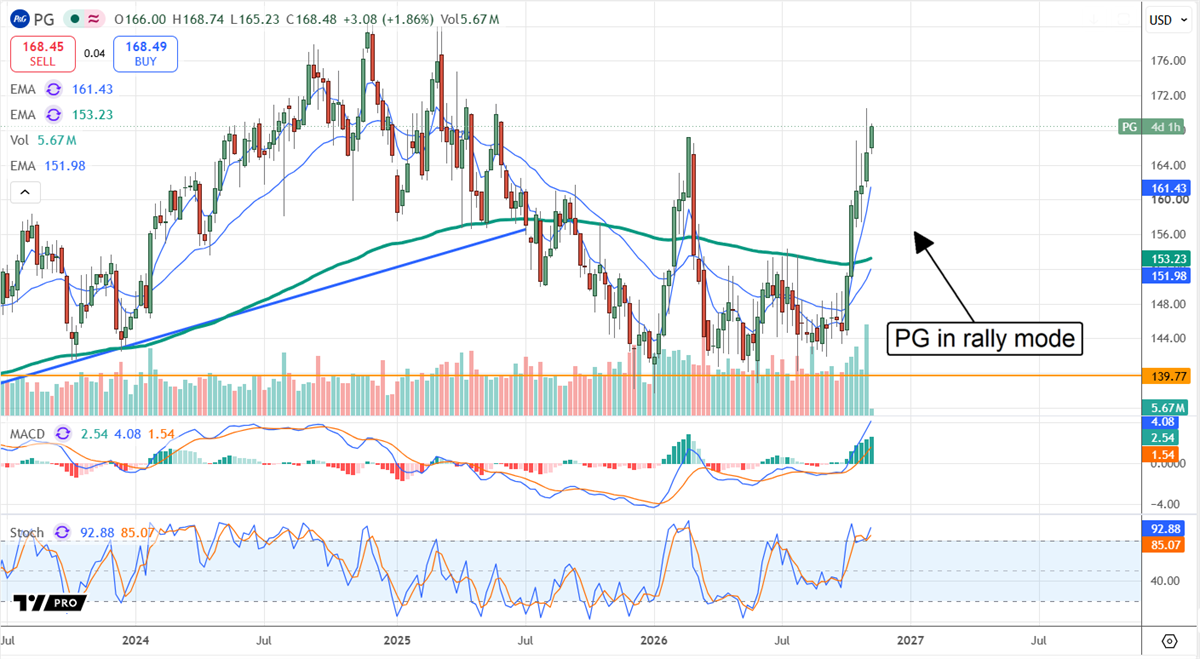
Insider promoting of Procter & Gamble (NYSE: PG) shares just isn’t a pink flag. The spotty, generally massive, share gross sales are linked to prearranged buying and selling plans, meant to take care of diversification and handle choices workouts tied to share-based compensation.
Executives nonetheless personal a big stake, whereas the corporate’s established enterprise and powerful money stream assist offset ongoing price pressures.
The primary hurdle for Procter & Gamble is customers shifting to cheaper alternate options, which might strain gross sales and profitability. Nonetheless, the corporate’s broad product portfolio IT-wanted-a-reason-to-buy/” goal=”_blank” rel=”noopener”>provides IT a bonus, permitting IT to serve budget-conscious customers with out relying solely on premium-priced merchandise.
Analysts are bullish on PG stock. Of the 26 analysts masking Procter & Gamble, 15 fee IT a Purchase and 11 a Maintain, giving the inventory a Reasonable Purchase consensus ranking. Worth targets have additionally climbed, with the common round $170. Continued upward revisions might sign higher confidence within the firm’s outlook and help additional share-price positive aspects.
Buyers ought to contemplate Procter & Gamble’s cash flow and profitability, which help wholesome capital returns. Capital returns embody share buybacks and dividends, together with distribution progress.
The corporate is a Dividend King, yielding around 2.6%, and in a position to maintain annual distribution will increase for the foreseeable future.
Procter & Gamble’s acquisition of Thorne HealthTech might drive progress by increasing its presence in premium, practitioner-focused, subscription-based healthcare. Nonetheless, rising enter prices have already pressured margins, and additional will increase might weigh on profitability.
Firms in This Article:
| Firm | Present Worth | Worth Change | Dividend Yield | P/E Ratio | Consensus Ranking | Consensus Worth Goal |
|---|---|---|---|---|---|---|
| Brinker Worldwide (EAT) | $197.30 | -1.7% | N/A | 17.37 | Reasonable Purchase | $249.80 |
| Liquidia (LQDA) | $58.12 | +5.3% | N/A | 24.98 | Maintain | $74.38 |
| Procter & Gamble (PG) | $168.02 | +0.2% | 2.59% | 25.30 | Reasonable Purchase | $170.57 |
Expertise
Thomas Hughes has been a contributing writer for InsiderTrades.com since 2019.
- Skilled Background: Thomas Hughes is the Managing Associate of Passive Market Intelligence LLC, a market analysis platform he launched in 2023 with the mission: “We watch the market so you do not have to.” He has labored as a blogger, inventory market commentator, and impartial analyst since 2010 and has been actively concerned in buying and selling and investing since 2005.
- Credentials: He holds an Affiliate of Arts in Culinary Technology—coaching that honed his self-discipline, consideration to element, and talent to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Expertise: Thomas has been writing about Finance and investing since 2011, when he found IT might be greater than a private ardour—IT might be a career. He’s been a contributing author for InsiderTrades.com since 2019.
- Writing Focus: He specializes within the S&P 500, small-cap shares, dividend and high-yield methods, client staples, retail, Technology, oil, and cryptocurrencies. His evaluation blends chart-based technical setups with key basic insights, serving to readers determine actionable tendencies.
- Funding Strategy: Thomas takes a hybrid strategy that mixes technical evaluation with deep basic analysis. He typically writes about macroeconomic shifts, earnings tendencies, and sentiment-based buying and selling alerts.
- Inspiration: Thomas first turned occupied with shares after attending a seminar on the best way to purchase and promote your individual shares. That occasion opened his eyes to the market’s potential and sparked a lifelong curiosity in investing.
- Enjoyable Truth: Thomas took up mannequin railroading accidentally just a few years in the past—and now he can’t cease working the rails.
- Areas of Experience: Technical and basic evaluation, S&P 500, retail and client sectors, dividends, market tendencies
Schooling
Affiliate of Arts in Culinary Technology
👇Observe extra 👇
👉 bdphone.com
👉 ultractivation.com
👉 trainingreferral.com
👉 shaplafood.com
👉 bangladeshi.help
👉 www.forexdhaka.com
👉 uncommunication.com
👉 ultra-sim.com
👉 forexdhaka.com
👉 ultrafxfund.com
👉 bdphoneonline.com
👉 dailyadvice.us